LUNARTULIP RESEARCHINDUSTRY CHANGE · COMPANY CASH FLOWS
English
AI基础设施 · 研究01

NVIDIA换帅之后,AI产业链哪些增长预期需要重估?

客户融资、HBM扩产与CPO变局:从产业关系推演公司现金流

2026年11月18日 · 财报后更新

基于AlphaMap关系数据与公开披露

LUNARTULIP RESEARCH / 01ALPHAMAP FIRST CASE · v1.4.0
LunarTulip Research AI 基础设施产业深度报告封面

THE INDUSTRY DEEP DIVE

产业深度报告,打开即读

完整论证、图表、模型口径与原始资料集中在这份 26 页报告中。沿客户融资、HBM 采购与 CPO 部署,逐层核对增长如何进入公司收入与现金流。

26 PAGES55 SOURCESRO-ALPHAMAP-CASE-001
在线翻阅 · 26 页完整报告获取复算资料 ↗
报告内页预览第 2、8、16 页
在本页展开完整 26 页 PDF ↘

若设备无法显示内嵌 PDF,可打开完整报告或下载阅读。

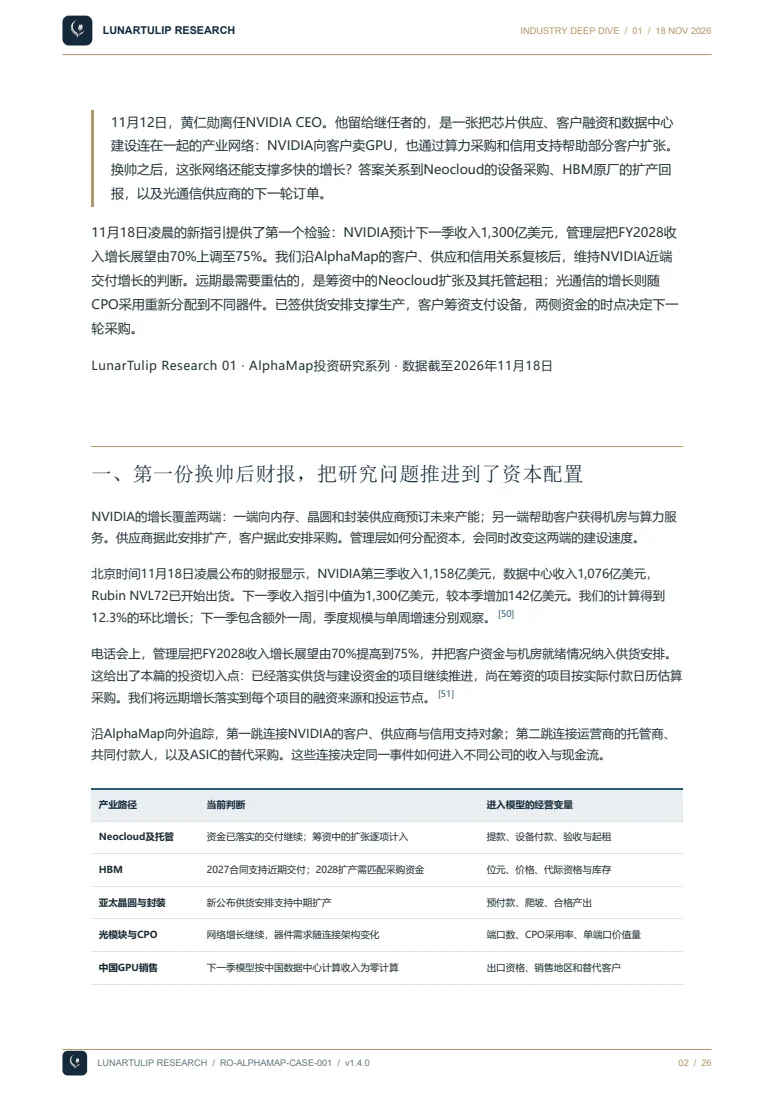
11月12日,黄仁勋离任NVIDIA CEO。他留给继任者的,是一张把芯片供应、客户融资和数据中心建设连在一起的产业网络:NVIDIA向客户卖GPU,也通过算力采购和信用支持帮助部分客户扩张。换帅之后,这张网络还能支撑多快的增长?答案关系到Neocloud的设备采购、HBM原厂的扩产回报,以及光通信供应商的下一轮订单。

11月18日凌晨的新指引提供了第一个检验:NVIDIA预计下一季收入1,300亿美元,管理层把FY2028收入增长展望由70%上调至75%。我们沿AlphaMap的客户、供应和信用关系复核后,维持NVIDIA近端交付增长的判断。远期最需要重估的,是筹资中的Neocloud扩张及其托管起租;光通信的增长则随CPO采用重新分配到不同器件。已签供货安排支撑生产,客户筹资支付设备,两侧资金的时点决定下一轮采购。

LunarTulip Research 01 · AlphaMap投资研究系列 · 数据截至2026年11月18日

一、第一份换帅后财报,把研究问题推进到了资本配置

NVIDIA的增长覆盖两端:一端向内存、晶圆和封装供应商预订未来产能;另一端帮助客户获得机房与算力服务。供应商据此安排扩产,客户据此安排采购。管理层如何分配资本,会同时改变这两端的建设速度。

北京时间11月18日凌晨公布的财报显示,NVIDIA第三季收入1,158亿美元,数据中心收入1,076亿美元,Rubin NVL72已开始出货。下一季收入指引中值为1,300亿美元,较本季增加142亿美元。我们的计算得到12.3%的环比增长;下一季包含额外一周,季度规模与单周增速分别观察。[50]

电话会上,管理层把FY2028收入增长展望由70%提高到75%,并把客户资金与机房就绪情况纳入供货安排。这给出了本篇的投资切入点:已经落实供货与建设资金的项目继续推进,尚在筹资的项目按实际付款日历估算采购。我们将远期增长落实到每个项目的融资来源和投运节点。[51]

沿AlphaMap向外追踪,第一跳连接NVIDIA的客户、供应商与信用支持对象;第二跳连接运营商的托管商、共同付款人,以及ASIC的替代采购。这些连接决定同一事件如何进入不同公司的收入与现金流。

产业路径当前判断进入模型的经营变量
Neocloud及托管资金已落实的交付继续;筹资中的扩张逐项计入提款、设备付款、验收与起租
HBM2027合同支持近期交付;2028扩产需匹配采购资金位元、价格、代际资格与库存
亚太晶圆与封装新公布供货安排支持中期扩产预付款、爬坡、合格产出
光模块与CPO网络增长继续,器件需求随连接架构变化端口数、CPO采用率、单端口价值量
中国GPU销售下一季模型按中国数据中心计算收入为零计算出口资格、销售地区和替代客户
开放模型生态公开产品投入继续支撑GPU使用场景研发投入、开发者采用与算力采购
图1|六条研究路径连接公司、交易安排与财务变量。实线为披露关系或指引,虚线为本文推导的机制;对应来源逐项保留在global_path_evidence.json。

判断为截至2026年11月18日的研究意见。FY2028为NVIDIA财年;后文2028年HBM模型使用自然年。各行按本节及后文来源分别论证。

二、CoreWeave的订单支持,沿着付款日历传到托管商

NVIDIA与CoreWeave的剩余算力采购协议初始价值63亿美元,延续至2032年4月。CoreWeave完成约定容量交付并满足服务条件后,NVIDIA购买适用范围内的剩余容量。这项安排改善指定项目的收入保障,支持运营商向贷款人展示未来收款来源。[2]

建设发生在经营收款之前。CoreWeave前三季度经营现金流56.38亿美元,现金固定资产及软件投入235.58亿美元,现金覆盖率为23.9%;同期净融资213.46亿美元。外部资金已经承担了扩张中的大部分资本需求。管理层预计随后三个月收到90亿美元预付款及押金,到账节奏决定下一批设备付款的资金余量。[3][5]

我们把这项依赖展开为一个付款压力测试。假设90亿美元中有20%推迟到账,当期少收18亿美元;再投入10亿美元可即时动用的替代资金,剩余8亿美元需要新增融资或付款展期。足额贷款可以维持采购节奏,并通过利息减少权益端现金;按100个基点的额外年融资成本计算,每10亿美元借款增加1,000万美元年利息。这些参数可由读者替换。[3][5]

11月17日CFO说明把Neocloud支持的生效顺序写得更清楚:客户先筹得采购资金,设备完成部署、投运和验收,约定支持随之生效。管理层在问答中确认这套机制此前就在执行。我们的基准延续项目融资与采购的逐项判断,把资金到位作为预计交付的具体依据。[51][52]

图2|从NVIDIA客户与信用关系,追到共同付款人、托管商和替代采购。原图保留13项AlphaMap既有关系与9项公开补证;本轮新增制造与技术证据另见来源50—54。关系方向与合同作用分别保留。

三、CORZ的新客户正在扩展,当前收款仍集中于CoreWeave

从CoreWeave再走一跳,Core Scientific(CORZ)的收入结构就变得重要。截至9月底,CORZ全部托管收入来自CoreWeave,后者贡献集团前三季度约84%的收入。CoreWeave租用的590MW中已有485MW计费,约82%;余下105MW的起账时间继续影响新增托管收入。[6][7]

CORZ未来合同引入了另一组客户:AMD直接承租377MW,另一家Neocloud承租152MW,并取得AMD对特定租约的条件信用支持。把这些合同与CoreWeave放在同一容量表里,CoreWeave约占53%。新增租约当时处于起租前,未来客户分散通过2027—2028年的交付逐步进入收入。[6][7][49]

因此,我们判断CORZ的近期现金流主要受CoreWeave的付款与抵扣条款影响;新增529MW的收入增长则跟随各租约的融资、建设和起租进度。按达到50%抵扣上限的适用租约举例,每100美元合资格月费当期收现50美元;抵扣耗尽、月费保持不变时,当期收现升至100美元。之后的现金继续按项目债务契约支付利息、摊还与储备。[7][8]

替代支持方还连接了其他建设路径。Google向Akela指定租约提供条件信用支持;Broadcom参与的630亿美元设备SPV融资安排连接Anthropic的XPU与网络采购。这些合同说明,部分ASIC客户获得了其他支持方的筹资安排。我们在行业需求判断中同时考虑GPU与ASIC扩张,按每项合同核对支持范围和资金交割,再评估其设备采购时点。[11][39]

图3|CORZ当前收入、签约容量与CoreWeave计费进度。约53%对应未来签约IT容量,约82%对应CoreWeave的590MW合同;截至9月底的托管收入集中度为100%。

四、内存和封装已有供货安排,新增需求要追到出资人

截至10月25日,NVIDIA的供应与产能承诺从上一季2,790亿美元升至3,900亿美元,增加1,110亿美元、约39.8%,增量主要涉及多年内存采购。这些已签安排给供应商规划未来产能提供了依据。本轮我们把供货承诺与客户融资分别列账:前者安排生产,后者支付设备。[52]

11月17日新公布的供应链安排又延伸到亚太基板和封装。Kinsus计划按公告口径,在当前水平基础上扩大逾3.5倍的NVIDIA专用ABF基板产能,新增产能目标在2028年第三季;Amkor既有近30亿美元协议包含扩产预付款;SPIL获得数十亿美元支持,扩大至2029年中的专用先进封装能力。公司延续多年采购和预付安排,制造伙伴据此推进建设。[53]

我们维持2027年HBM交付受到合同支持的判断。Micron披露,绝大多数2027年HBM位元供给已完成协议,并约定显著的同比提价。2028年的扩产回报继续由合格产出、客户采购量和成交价格共同决定。[20]

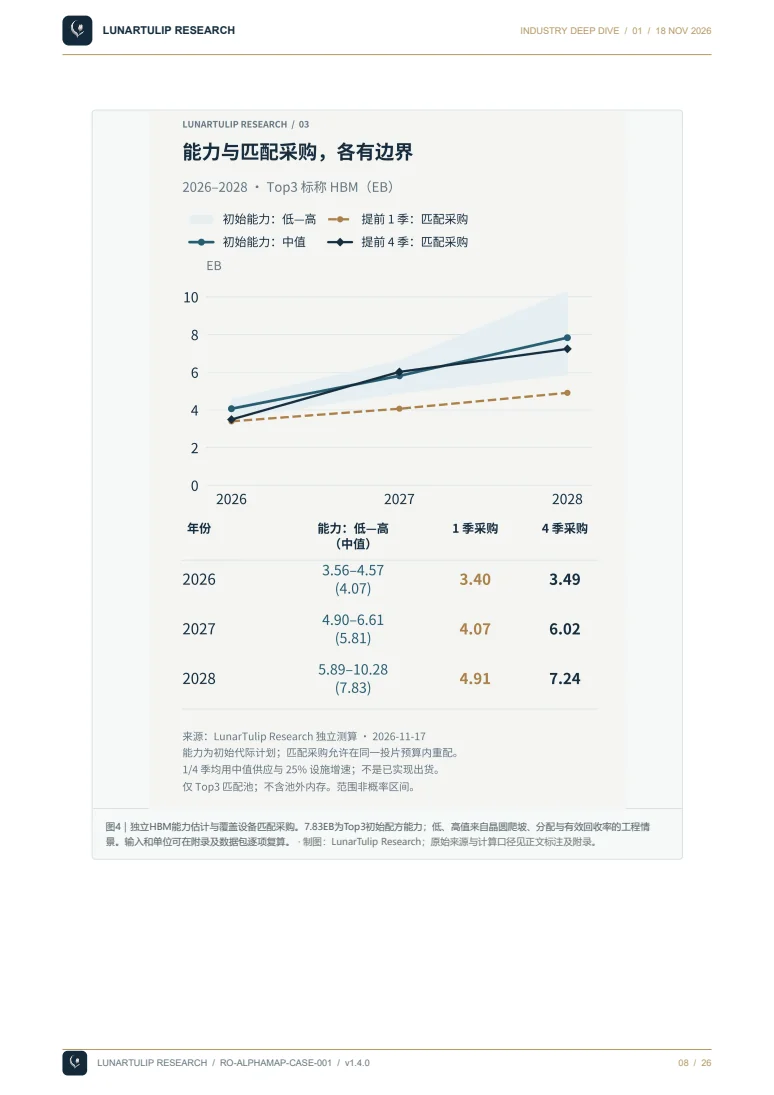
独立供给模型从全年晶圆加工量、每片有效产出和代际配方推算,2028年三家主要原厂的初始配方能力约7.83EB,工程低、高情景为5.89—10.28EB。需求模型把GPU与ASIC分开,覆盖设备在完整采购路径下需要约11.10EB;其中ASIC贡献2026—2028年新增设备数量的约75%。这些数量说明,供应商争取NVIDIA、AMD与自研芯片客户时,客户组合和合格代际会共同影响产能消化。[25][26][27][28]

我们据此优先评估已谈定量价、具备客户资格的HBM供货,再评估远期新增产线。对NVIDIA的供应链议价力,继续跟踪实际采购价格和可分配产能;对HBM行业需求,同时计入GPU与ASIC客户的采购资金。

图4|独立HBM能力估计与覆盖设备匹配采购。7.83EB为Top3初始配方能力;低、高值来自晶圆爬坡、分配与有效回收率的工程情景。输入和单位可在附录及数据包逐项复算。

五、2028年HBM采购差额,最终需要客户为库存出资

设备从采购到上电之间,买方需要垫付资本。固定设施IT容量年增25%、中值设备功率、相同期初库存和一季物理投运延迟,我们把采购窗口分别设为提前一季、两季和四季。2028年覆盖设备内嵌HBM分别为4.958、5.212和7.311EB,三条路径的年末已投运AI系统IT容量均为99.7GW。[36]

从提前一季改为提前一年,2028年采购流量增加2.354EB,约47.5%;年末未安装设备内嵌HBM增加4.433EB。按GPU和ASIC分别3万、1万美元的设备成本假设,较长采购窗口还多占用约2,174亿美元期末加速器资本。提前锁货把未来安装需求转成今天的订单,也把资本占用留在买方账上。

这组差额给出了远期HBM增长最需要验证的资金量级。IREN对应Microsoft项目的贷款按分批交付及先决条件提款,具备这种提款结构的项目需要依照里程碑安排接货。客户预付款、可提款额度和设备付款日历,因而进入我们的HBM采购模型。[14][15]

产品配置同样影响需求。固定同一批2028年设备数量,适用Ultra工程配置与MI450X/MI455X选择使HBM从11.42EB变为11.10EB,减少约0.32EB、2.8%。固定设备实验给出配置变化的量级,采购窗口实验给出提前持货的资金规模。我们将客户资金、投运速度和产品配置分别计算,再判断原厂的产能消化。[31][32][33][34]

图5|同一组投运假设下的采购政策敏感性。2.354EB是外生采购窗口带来的年度流量差;2028年的设施增长、功率和库存假设见正文。对应年末库存差为4.433EB。

把同一个投资主张放进不同条件

当年设备内嵌HBM4.958EB · 2028
其中Top3匹配吸收4.909EB · 2028
期末未安装设备内嵌HBM1.334EB · 2028
期末已装AI系统IT99.7GW · 2028

27个组合均由同一冻结模型完整运行;没有前端插值。内存/面积采用中值,物理延迟固定1季。25%属于较快设施扩张;数字计量覆盖设备,未校准为全行业发生概率。

六、CPO开始进入生产网络,光通信需要重算每个端口的价值

本次电话会披露,CPO已经进入生产网络。管理层披露,季度网络收入超过210亿美元,CPO scale-out已进入量产,Lambda宣布首个连接超过一万枚GB300 GPU的生产部署。我们据此维持网络互连建设继续推进的判断,并把器件结构变化纳入光通信公司的收入假设。[51]

在可由CPO与可插拔方案相互替换的同一组scale-out光连接中,可插拔器件收入可写成“当期交付端口数×可插拔方案占比×合格份额×每端口供货价值”;CPO器件使用同一端口基数,再乘以CPO采用率、合格份额与每端口供货价值。集群继续扩大,同时提高CPO采用率时,两类器件的订单可以出现不同变化。

我们用一张标准化测算说明量级:假设同一组可替换连接的当期交付端口数增加50%,CPO占比由10%升至30%,单端口价值和份额保持不变,可插拔相关端口增长为1.5×70%÷90%−1,约16.7%;CPO端口增长为1.5×30%÷10%−1,即350%。具体公司再代入其器件范围、客户资格与价格,将端口增长转换成收入。

这条路径给出了光通信的投资分化:继续看好网络建设投入,按可插拔模块、光引擎及其他实际供货器件分别估算增长。NVIDIA继续推进CPO,会把部分新增互连价值分配给具备相应供货资格的厂商。

本节端口例题为标准化敏感性,50%、10%及30%均为显式假设。单端口供货价值、客户资格和产品边界决定各公司的结果。

七、中国销售与开放生态,分别进入销售地区和研发投入

中国销售已经进入新指引。NVIDIA本季对中国的Hopper数据中心产品销售为24亿美元,下一季指引按中国数据中心计算收入为零计算。以本季总收入扣除这24亿美元,比较基数为1,134亿美元;1,300亿美元指引中值相对这一基数增加166亿美元,约14.6%。这项计算表明,下一季总收入增长主要由其他销售与产品承担。[50][52]

对供应链模型,我们从下一季中国计算销售中取零,并将海外订单、产品组合和交付时点分别更新。董事会同日成立国家安全与出口管制监督委员会,出口资格与地区渠道因此成为持续更新的公司治理变量。[54]

开放生态继续沿产品投入推进。NVIDIA在11月16日推出Nemotron for Science,将开放模型接入科学研究场景。我们的研究判断是,更多可部署模型可以扩大GPU的使用场景;后续用开发者采用、实际服务负载和采购订单检验这一需求路径。[55]

把销售地区与开放模型分开,可以保留各自的经济因果:中国计算产品收入由出口资格和订单决定,开放模型通过应用采用影响算力使用。两条路径分别修改需求假设,避免在公司总收入中重复计算同一终端负载。

图6|季度收入规模桥接:本季1,158亿美元,扣除中国Hopper销售24亿美元得比较基数1,134亿美元;下一季指引中值1,300亿美元。下一季含额外一周。14.6%为对调整后基数的规模比较。

投资主张:近端增长继续,远端按资金和器件结构重新定价

我们在换帅后的第一个业绩节点,维持NVIDIA近端交付增长、HBM近期合同交付和网络互连建设继续推进的判断。新指引、已签供货安排和生产部署分别支持这三项结论。

远期增长进入公司比较时,我们将已落实采购、建设与提款安排的项目,按合同和预计交付时间计入收入;对持续依赖外部融资的扩张,逐期核对可支付金额与设备付款节点。CoreWeave的资金到账连接CORZ的起租与收现,HBM原厂的新增产能连接客户持货资本,光通信收入连接CPO采用后的器件价值。这些变量决定同一AI资本开支周期里各家公司能兑现多少增长。

下一轮信息更新围绕具体经营结果展开:运营商公布提款和预付款到账,就按到账额、用途与设备付款日更新采购排期;新增容量验收起租,就更新托管收入;HBM客户完成代际认证和量价协议,就更新原厂产能消化;CPO部署披露端口与供货器件,就更新光通信产品收入。

这也是本篇使用AlphaMap的研究价值:从一家公司出发,找到共同付款人、支持工具和第二层供应关系,再让每条关系改变一个可以检查的财务假设。本篇保留现有关系与公开补证的来源,读者可以从合同追到输入,从输入复算结论,并据此提出自己的投资判断。

LUNARTULIP RESEARCH

LunarTulip Research研究产业变化如何通过客户、合同与资本开支传到公司现金流。本篇以AlphaMap已有关系为起点,补核公开证据并独立测算,使融资支持、共同客户和替代采购进入同一项投资判断。

从你覆盖的一家公司和一条待验证的投资判断开始:共同客户、扩产兑现,或融资变化如何影响下一轮采购。

模型、证据与可复算附录

本轮更新与模型身份

本轮以北京时间2026年11月18日的新披露更新公司判断,HBM数量情景沿用独立模型4.1。FY2028增长展望属于管理层指引;自然年2028的设备量、设施增长、库存政策与远期BOM是分别列示的研究假设。数值按其原始实验分别解释。

模型覆盖高端云加速器。2028年Top3初始配方能力7.83EB;采购窗口1/2/4季对应4.958/5.212/7.311EB的覆盖设备内嵌量。原厂同期出货还受到其他客户及原始HBM、在制品库存变动影响。全球最可能采购路径及与11月17日外部研究三项降幅的同口径裁决,沿既有研究台账继续补证。

CPO例题使用同组可替换scale-out连接,端口数为当期交付流量。Kinsus倍数沿公告“by more than 3.5x over current levels”登记,本文未将其转为晶圆或芯片产出。

本轮更新与模型身份

本轮以北京时间2026年11月18日的新披露更新公司判断,HBM数量情景沿用独立模型4.1。FY2028增长展望属于管理层指引;自然年2028的设备量、设施增长、库存政策与远期BOM是分别列示的研究假设。数值按其原始实验分别解释。

模型覆盖高端云加速器。2028年Top3初始配方能力7.83EB;采购窗口1/2/4季对应4.958/5.212/7.311EB的覆盖设备内嵌量。原厂同期出货还受到其他客户及原始HBM、在制品库存变动影响。全球最可能采购路径及与11月17日外部研究三项降幅的同口径裁决,沿既有研究台账继续补证。

CPO例题使用同组可替换scale-out连接,端口数为当期交付流量。Kinsus倍数沿公告“by more than 3.5x over current levels”登记,本文未将其转为晶圆或芯片产出。

本轮更新与模型身份

本轮以北京时间2026年11月18日的新披露更新公司判断,HBM数量情景沿用独立模型4.1。FY2028增长展望属于管理层指引;自然年2028的设备量、设施增长、库存政策与远期BOM是分别列示的研究假设。数值按其原始实验分别解释。

模型覆盖高端云加速器。2028年Top3初始配方能力7.83EB;采购窗口1/2/4季对应4.958/5.212/7.311EB的覆盖设备内嵌量。原厂同期出货还受到其他客户及原始HBM、在制品库存变动影响。全球最可能采购路径及与11月17日外部研究三项降幅的同口径裁决,沿既有研究台账继续补证。

CPO例题使用同组可替换scale-out连接,端口数为当期交付流量。Kinsus倍数沿公告“by more than 3.5x over current levels”登记,本文未将其转为晶圆或芯片产出。

本轮更新与模型身份

本轮以北京时间2026年11月18日的新披露更新公司判断,HBM数量情景沿用独立模型4.1。FY2028增长展望属于管理层指引;自然年2028的设备量、设施增长、库存政策与远期BOM是分别列示的研究假设。数值按其原始实验分别解释。

模型覆盖高端云加速器。2028年Top3初始配方能力7.83EB;采购窗口1/2/4季对应4.958/5.212/7.311EB的覆盖设备内嵌量。原厂同期出货还受到其他客户及原始HBM、在制品库存变动影响。全球最可能采购路径及与11月17日外部研究三项降幅的同口径裁决,沿既有研究台账继续补证。

CPO例题使用同组可替换scale-out连接,端口数为当期交付流量。Kinsus倍数沿公告“by more than 3.5x over current levels”登记,本文未将其转为晶圆或芯片产出。

本轮更新与模型身份

本轮以北京时间2026年11月18日的新披露更新公司判断,HBM数量情景沿用独立模型4.1。FY2028增长展望属于管理层指引;自然年2028的设备量、设施增长、库存政策与远期BOM是分别列示的研究假设。数值按其原始实验分别解释。

模型覆盖高端云加速器。2028年Top3初始配方能力7.83EB;采购窗口1/2/4季对应4.958/5.212/7.311EB的覆盖设备内嵌量。原厂同期出货还受到其他客户及原始HBM、在制品库存变动影响。全球最可能采购路径及与11月17日外部研究三项降幅的同口径裁决,沿既有研究台账继续补证。

CPO例题使用同组可替换scale-out连接,端口数为当期交付流量。Kinsus倍数沿公告“by more than 3.5x over current levels”登记,本文未将其转为晶圆或芯片产出。

本轮更新与模型身份

本轮以北京时间2026年11月18日的新披露更新公司判断,HBM数量情景沿用独立模型4.1。FY2028增长展望属于管理层指引;自然年2028的设备量、设施增长、库存政策与远期BOM是分别列示的研究假设。数值按其原始实验分别解释。

模型覆盖高端云加速器。2028年Top3初始配方能力7.83EB;采购窗口1/2/4季对应4.958/5.212/7.311EB的覆盖设备内嵌量。原厂同期出货还受到其他客户及原始HBM、在制品库存变动影响。全球最可能采购路径及与11月17日外部研究三项降幅的同口径裁决,沿既有研究台账继续补证。

CPO例题使用同组可替换scale-out连接,端口数为当期交付流量。Kinsus倍数沿公告“by more than 3.5x over current levels”登记,本文未将其转为晶圆或芯片产出。

本附录把原始披露、外部研究估计和本文假设分别列示。模型4.1的计算已冻结;1、2、4季采购政策共同展示,未赋予未经校准的概率。

A|从设备、晶圆到库存和现金的计算链
环节计算与单位关键输入身份
需求买方/平台数量 × 产品组合 → 各SKU年度需求2026估计基期;后续增长、客户分期和组合为研究假设 [28][29][48]
HBM供给Σ 晶圆片数 × 每片晶粒数 × Gb/晶粒 ÷ 8 × 有效合格回收率 ÷ 10⁹ → 标称EB原厂建设计划、研究机构容量估计及自有爬坡/良率假设 [20][25][26][27]
产品匹配按HBM代际、晶圆预算及工程BOM求兼容供给;可重配投片需提前规划与认证资格损失已含在有效回收率,基准不重复打折;最大能力不自动成为实际产量
采购与安装季度采购 − 季度安装 = 未安装库存变化;投运存量 = 上期存量 + 安装 − 退役采购前瞻1/2/4季与物理延迟1季分开;开仓库存固定,按SKU/来源季度跟踪
面积Σ 百万台设备 × 每台mm² → 合格逻辑硅m²含compute/IO/有效逻辑层;排除HBM、interposer及基板;不是投片面积
功率额定设备出货GW → 系统IT安装GW → 按负载/PUE计算TWh年出货、期末在用存量、平均场址负荷与年度电量分别记账
收入/资本占用位元 × 相应价格;库存设备数 × 相应成本收入确认、原始HBM/WIP变动及真实采购价格仍需单独桥接;本文成本为情景刻度

标称GB/EB沿用供需两侧一致的行业容量标签,不将一侧GiB换成十进制GB后与另一侧直接比较。Blackwell/Rubin双计算晶粒仍是一枚GPU;TPU8i Max每封装两枚底层设备,不重复放大每设备显存。[30][31]

B|决定结论的前置假设
参数基准与范围依据/重要边界
2025设施IT全球82GW;AI25GW/常规57GW82GW为IEA估计;AI与常规拆分为本文假设 [36]
设施扩张全球IT年增20% / 25% / 30%25%为较快扩张情景。2030约250GW,高于IEA外部174GW预测;未以IEA2030数值校准 [36][37][38]
AI就绪及地域匹配基准新增可用IT 100%适配AI;另列85%需要供电、冷却、网络与地点均可用;全球可互换是偏积极边界
系统开销与电量系统IT/加速器额定功率1.45;敏感性1.25—1.65;新增AI负载0.60、PUE1.15PUE只用于电量,不放大可安装IT容量;整机/机架规格不能当芯片TDP [23][45][46]
存量与寿命开仓未装5.672GW;50%H200/50%B200数量代理;新设备寿命5年非实测库存;各采购政策使用相同开仓。旧AI25GW分5年均匀退役
采购提前1、2、4季;物理可投运延迟1季不得把安装延迟机械设成全球唯一采购规则;设备可就绪后继续留在库存
未来BOM基准24Gb续接;未来480GB是384/576GB配置各半的群体平均不是已发布480GB单一SKU或10-Hi产品;32Gb切换仅作单独压力情景
内存库存原始HBM与WIP净变基准为0设备内嵌量可以代理覆盖设备吸收,不是整个HBM市场同期出货或收入
未单独约束逻辑前道、CoWoS、基板及板卡吞吐目前未形成逐工艺/客户的全球产能面板;面积为派生需求映射
2029—2030产能、产品与2031采购终值采用显式续接假设远期误差更大;不能将年度表解读为已验证的全市场点预测
C|需求路径与2028年设备配置
年份NVIDIA GPU其他GPUGoogle TPU其他ASIC合计/百万枚ASIC占比
20267.700.843.423.8115.7845.9%
20279.231.436.336.4823.4854.6%
202810.162.018.869.0830.1159.6%
202910.672.5111.0811.3535.6063.0%
203010.673.0113.3013.6240.5966.3%

以上为供应、资金和设施约束前的需求路径,不是观察到的订单。2026基期由2027外部公开摘要与增速反推,仍是估计。GPU/ASIC成本比3:1且单价不变时,2028预算须较2026增加65.7%;若单位成本、云商自建/外租结构改变,预算桥须同步改动。[28]

具名客户项目只能解释部分增长。AWS的额外200万枚GPU按交付区间分期;Anthropic的5GW并非全体Google TPU需求。客户池残余增速保留为假设,未把某一云商全公司CapEx直接除以GPU价格。[29][48]

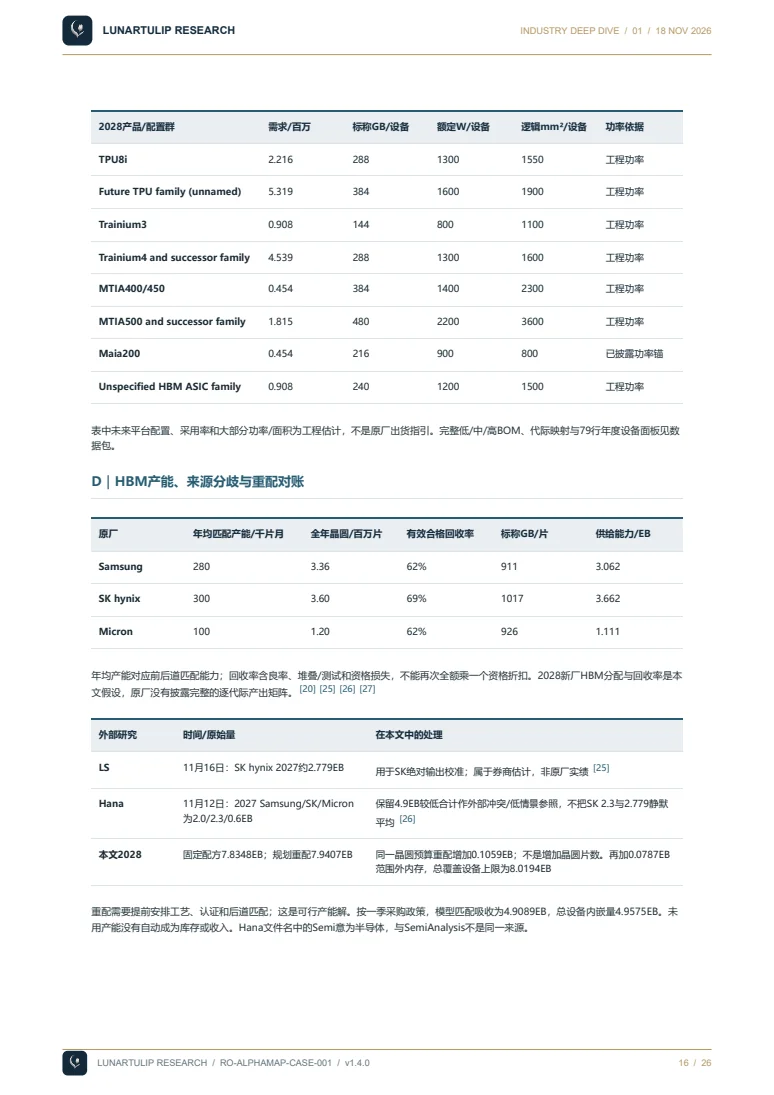
2028产品/配置群需求/百万标称GB/设备额定W/设备逻辑mm²/设备功率依据
B300 HGX0.12228811001650已披露功率锚
GB300 NVL72 GPU portion0.18328814001650已披露功率锚
Rubin GPU1.91028818001650工程功率
Rubin Ultra architecture branches2.86548028003300工程功率
Post-2027 GPU family (unnamed)5.07948032003300工程功率
MI450X0.30128818002870工程功率
MI455X0.50243218002870工程功率
Post-MI400 GPU family (unnamed)1.20548024003200工程功率
TPU8t1.33021612001550工程功率
TPU8i2.21628813001550工程功率
Future TPU family (unnamed)5.31938416001900工程功率
Trainium30.9081448001100工程功率
Trainium4 and successor family4.53928813001600工程功率
MTIA400/4500.45438414002300工程功率
MTIA500 and successor family1.81548022003600工程功率
Maia2000.454216900800已披露功率锚
Unspecified HBM ASIC family0.90824012001500工程功率

表中未来平台配置、采用率和大部分功率/面积为工程估计,不是原厂出货指引。完整低/中/高BOM、代际映射与79行年度设备面板见数据包。

D|HBM产能、来源分歧与重配对账
原厂年均匹配产能/千片月全年晶圆/百万片有效合格回收率标称GB/片供给能力/EB
Samsung2803.3662%9113.062
SK hynix3003.6069%10173.662
Micron1001.2062%9261.111

年均产能对应前后道匹配能力;回收率含良率、堆叠/测试和资格损失,不能再次全额乘一个资格折扣。2028新厂HBM分配与回收率是本文假设,原厂没有披露完整的逐代际产出矩阵。[20][25][26][27]

外部研究时间/原始量在本文中的处理
LS11月16日:SK hynix 2027约2.779EB用于SK绝对输出校准;属于券商估计,非原厂实绩 [25]
Hana11月12日:2027 Samsung/SK/Micron为2.0/2.3/0.6EB保留4.9EB较低合计作外部冲突/低情景参照,不把SK 2.3与2.779静默平均 [26]
本文2028固定配方7.8348EB;规划重配7.9407EB同一晶圆预算重配增加0.1059EB;不是增加晶圆片数。再加0.0787EB范围外内存,总覆盖设备上限为8.0194EB

重配需要提前安排工艺、认证和后道匹配;这是可行产能解。按一季采购政策,模型匹配吸收为4.9089EB,总设备内嵌量4.9575EB。未用产能没有自动成为库存或收入。Hana文件名中的Semi意为半导体,与SemiAnalysis不是同一来源。

E|2026—2030年完整物理量输出

提前一季采购

年份制造/百万设备内嵌HBM/EB逻辑面积/千m²当年额定出货/GW期末AI系统IT/GW全数据中心/TWh
202615.343.49422.3117.2644.27545
202714.884.09825.9521.6768.82683
202813.454.95830.9025.9899.67860
202915.496.09537.5631.81138.501075
203020.748.19350.0042.14187.311346

提前四季采购

年份制造/百万设备内嵌HBM/EB逻辑面积/千m²当年额定出货/GW期末AI系统IT/GW全数据中心/TWh
202615.783.59222.9317.7544.36545
202722.036.06738.4232.0868.82684
202819.837.31145.5838.3299.67860
202918.077.11243.8337.11138.501075
203029.0711.48670.0959.08187.311346

两表固定25%设施年增、中值功率、一季物理延迟及相同开仓。单季政策2026—2030累计逻辑硅面积约16.67万m²。2030设备额定出货42.14GW、期末AI系统IT187.31GW、全数据中心IT250.24GW和全年1346TWh分别回答不同问题;它们不能拿同一个34%去比较。

IEA外部2030预测为全数据中心IT约174GW、场址额定容量226GW、全年945TWh;本文较快扩张路径并未用这些远期预测反推参数。读者可直接用20%或更低设施路径检查结论。2029—2030仍受未发布产品、后续HBM工艺和产能续接假设影响。[36]

F|库存与融资:流量不能替代存量
提前/季当年内嵌/EB期末未装/百万设备期末未装HBM/EB未装系统IT/GW已装AI IT/GW
14.95753.6181.33410.13899.667
25.21247.4242.73720.80299.667
47.311115.6435.76743.82999.667

四季相对一季多采购2.3536EB;期末多持有4.4331EB、1,202.44万设备。它们是流量与存量,不能互换。相同投运GW也不要求已安装设备的批次或HBM总量完全相同。

ASIC假设单价GPU假设单价额外期末加速器资本/十亿美元
$5,000$15,000108.7
$10,000$30,000217.4
$15,000$45,000326.1

价格为归一化假设,成本指数按GPU:ASIC=3:1;额外库存约485.88万GPU、716.56万ASIC。资本占用不是年度新增CapEx、已承诺融资、净债务或市值影响。

G|公司财务传导与反证条件
公司/关系可影响的财务项目传导成立的条件与验证
Samsung / Micron2027交付与价格;2028扩产回报已谈定量价提高可见度;订单不可撤销性、交付及库存仍需核对 [20][42]
NVIDIA → CoreWeave设备/服务交付、融资成本与资本开支节奏指定剩余容量购买有履约条件;不等于为公司全部债务担保 [2]
AMD / 未具名Neocloud → CORZ未来客户结构、建设融资与起租377MW AMD直租+152MW另一客户租约;AMD仅对后者指定租约提供条件支持。截至9月底未起租,当前托管收入仍100%来自CoreWeave。590/(590+530)约53%为未来容量份额 [6][7][49]
CoreWeave → APLD / CORZ建设投入、起租、现金回收和债务覆盖具体项目融资、验收、起账与预付抵扣;不得因客户股价下跌直接扣租金 [6][7][9][10]
Microsoft → CRWV / NBIS / IREN共同预算敞口、交付与回款集中度核对独立容量和最终负载后去重;IREN Microsoft DDTL按4批及先决条件提款 [3][12][13][14]
Google → Akela / Fluidstack租约信用风险、保护范围和WULF稀释相应起租及违约条件、终止费/租约承接选择;不覆盖全部施工风险 [11]
Broadcom → SPV → AnthropicASIC交付、设备租赁和残值支持630亿美元承诺结构不等于全部已提款;Broadcom残值支持与一顺位贷款相等,非对全部金额无条件兜底 [39]
NVIDIA → SB Energy / OpenAI项目条件支持与新增支持意愿4.25GW IT/9阶段/担保上限1050亿美元;起租与特定违约触发。额外3.8GW是自主选择 [19]

换帅的增量效应须来自新订单、合同修订、支持选择或实际融资条件变化。基准未加入无证据的全球撤单折扣;这也不证明事件影响为零。已有供电延后及第三季度退款条款,不能倒归因为11月12日事件。[1][3][19]

传导渠道观察指标不能越过的推理
市场预期盈利预测、融资报价、估值与事件时点价格同跌不证明合同现金损失
融资预付到账、受限现金、可提款额度、替代资金与付款日历承诺额度不等于可用现金
经营交付/验收、起租、抵扣和收款相同根事件跨路径只计一次;未运行做空收益回测
H|SemiAnalysis两份材料的独立身份
材料可以确认本研究处理
旧图:11月13日对比11月2日 [16]2028HBM 9.0→6.4EB;2026—30逻辑硅面积五年显示值;2030功率122.8→80.7GW仅复算旧显示数值;功率范围待核,不作为新报告基数
独立的11月17日报告 [18]用户另行提供:累计面积−17%、2028HBM−30%、2030功率−34%尚未取得可复核原稿、绝对量与旧基期;身份保留独立
本文冻结模型2028有效产能7.8EB;同设施下政策采购5.0/5.2/7.3EB;同设备降配2.8%不使用上述外部基数/降幅;同范围对照成立前,具体幅度裁决未完成

下修相对的是先前预测,不等于同比需求下降。GPU份额下降、ASIC增长、HBM每设备减少与功率效率变化可以同时发生,幅度不必相同;应比较各自绝对量与驱动分解,不能给整条链贴一个统一标签。

I|保留的项目现金与债务图表

附录保留此前已核对的现金与合同模块:CoreWeave现金覆盖,Core Scientific计费、预付抵扣及单笔债务支付。它们解释公司间差异,不替代全球硬件数量模型。

01 crwv cash investment
02 corz billing
03 corz credit mechanism
04 corz debt service

CORZ债务例表使用票息7.75%、本金33亿美元、初始年摊还11.5%的合同参数;2029年11月15日首次摊还为条件日期,取决于相关租约起租、抵扣耗尽及合资格付款日。它不是公司完整自由现金流预测。[7][8]

J|关系与来源逐项对照
起点关系终点出处
NVIDIA设备供应CoreWeave既有AlphaMap关系 [3]
CoreWeave算力服务Microsoft既有AlphaMap关系 [3]
CoreWeave算力服务OpenAI既有AlphaMap关系 [3]
Nebius分批GPU服务Microsoft既有AlphaMap关系 [12][13]
IREN分批GPU服务Microsoft既有AlphaMap关系 [14][15]
Applied Digital项目托管CoreWeave既有AlphaMap关系 [9][10]
TeraWulf间接子公司Akela既有AlphaMap关系 [11]
Akela项目租约Fluidstack既有AlphaMap关系 [11]
Google条件信用支持Akela既有AlphaMap关系 [11]
TeraWulf权证对价Google既有AlphaMap关系 [11]
NVIDIA按条件购买剩余容量CoreWeave公开补证 [2]
Core Scientific项目托管CoreWeave公开补证 [6][7][8]
IREN云服务客户合同NVIDIA公开补证 [14]
SK hynix内存供应NVIDIA既有AlphaMap关系 [44]
Micron内存供应NVIDIA既有AlphaMap关系 [44]
SK hynixHBM4基底合作TSMC既有AlphaMap关系 [43]
Broadcom一顺位等额残值支持Financing SPV公开补证 [39]
BroadcomXPU与网络设备Financing SPV公开补证 [39]
Financing SPV设备租赁Anthropic公开补证 [39]
Core Scientific377MW直接承租/待起租AMD公开补证 [6][7][49]
Core Scientific152MW租约/待起租Undisclosed Neocloud公开补证 [6][7][49]
AMD仅152MW租约条件支持Core Scientific公开补证 [49]

图中13项既有关系用于发现研究路径,9项公开补证用于补齐当前合同与供应结构。箭头为服务、设备、权属或支持方向,不是统一现金方向;没有以路径数计算收益相关性或概率,也未声称本轮写入生产AlphaMap数据库。

原始来源与口径

  1. NVIDIA CEO transition2026-11-12 · Corporate announcement
  2. CoreWeave: NVIDIA capacity-purchase arrangement2025-09-15 · Form 8-K; specified residual capacity, through April 13, 2032
  3. CoreWeave Q3 2026 Form 10-Q2026-11-10 · Cash-flow statement: nine months ended September 30, 2026; named customers
  4. CoreWeave Q3 2026 results2026-11-10 · Results release
  5. CoreWeave Q3 2026 earnings call2026-11-10 · PDF pages 2 and 6; expected customer prepayments/deposits, not receipts
  6. Core Scientific Q3 2026 presentation2026-11-05 · Slides 4, 6, 9–13; leased and billable IT capacity, AMD-associated delivery expectations, CoreWeave contract book and construction credits
  7. Core Scientific Q3 2026 Form 10-Q2026-11-05 · Notes 6–7 and MD&A; uncommenced AMD-associated leases, current CoreWeave customer concentration, construction financing and contingent debt schedule
  8. Core Scientific Finance I LLC indenture2026-05-06 · Sections 4.23 and 14.01; principal and cash-use conditions
  9. Applied Digital Q1 FY2027 results2026-10-07 · Polaris Forge 1 delivery and completed project-note issuance
  10. Applied Digital FY2026 Form 10-K2026-07-29 · CoreWeave hosting scope and legal entities
  11. TeraWulf Q3 2026 Form 10-Q2026-11-06 · Akela/Fluidstack leases, Google recognition agreements and warrants
  12. Nebius Q3 2026 shareholder letter2026-11-12 · Microsoft NJ deployment schedule; companywide funding expectations
  13. Nebius Microsoft agreement summary2025-09-08 · Form 6-K; financing, phased delivery, grace period and alternative capacity
  14. IREN FY2026 Form 10-K2026-08-27 · Microsoft tranche prepayment/credit terms; NVIDIA cloud-services contract
  15. IREN Q1 FY2027 results2026-11-05 · Horizon rollout; scope and conditions of funding statements
  16. SemiAnalysis Accelerator Model: supplied comparison charts2026-11-13 model / 2026-11-02 previous version · Displayed chart values supplied to LunarTulip; circulated November 17. Original institutional report and underlying Excel not obtained. Calculations use displayed rounded values, not independently calibrated forecasts.
  17. SemiAnalysis Accelerator & HBM Model: official methodologyAccessed 2026-11-17 · Official model methodology and scope, not the underlying data for this revision
  18. Separate SemiAnalysis November 17 report: user-supplied headline summary2026-11-17, identified by user; original pending · Distinct from source 16. User reports -17% cumulative 2026–2030 accelerator logic area, -30% 2028 HBM, -34% 2030 data-centre power. Original text, baseline, metric perimeter and model inputs not yet obtained. No original-report audit claimed.
  19. NVIDIA Q2 FY2027 commitments and guarantees2026-08-26 filing; July 26 balances and August subsequent event · AI cloud service agreements, SB Energy/OpenAI conditional guarantees and optional further support; fiscal years
  20. Micron Q4 FY2026 prepared remarks2026-09-30 · Industry DRAM bit outlook, contracted 2027 HBM and capex-to-output lag; company expectations
  21. Microsoft FY2027 Q1 earnings call2026-10-28 · Customer demand, capital spending and third-party delivery timing; company CapEx includes finance leases
  22. Alphabet Q3 2026 earnings call2026-10-28 · 2026 cash capital spending guidance; server/network versus building mix; company outlook
  23. NVIDIA DGX B300 specificationsAccessed 2026-11-17 · Eight GPUs, reported 2.1 TB GPU memory, approximately 14 kW system power; hardware-equivalent illustration
  24. CoreWeave Vera Rubin MLPerf announcement2026-11-16 · Post-transition execution evidence in Available category; not a funding or all-roadmap guarantee
  25. LS Securities: SK hynix forecast and quarterly TSV model2026-11-16 · Original broker estimates, PDF p3. 2026/27 HBM2.117/2.779 nominalEB and annual processing2.205/2.85m wafers. Estimates, not issuer-reported actual output.
  26. Hana Securities: semiconductor industry capacity study2026-11-12 · Original broker estimates, printed p25. Supplier capacity paths and new-DRAM-fab scale. Filename Semi means semiconductor, not SemiAnalysis. Capacity timing and HBM allocation are modeled separately.
  27. Samsung Securities: HBM wafer geometry2026-06-02 · Printed p19 engineering estimates for dies per wafer and effective recovery; not measured factory yields.
  28. DIGITIMES: high-end cloud AI accelerator shipments2026-10-19 · Public original-publisher abstract anchors a backcast2026 estimate. Full paid report/count dictionary not accessed; 2026 is not an observed actual. Our forward growth assumptions are separate.
  29. NVIDIA Q2 FY2027 earnings call2026-08-26 · AWS additional2mGPUs over the stated multi-year period; no calendar-year delivery schedule. Revenue opportunity perGW includes multiple products, not a GPU ASP.
  30. Google TPU8t and TPU8i technical deep dive2026-04-22 · Official capacity/specification definitions. Neither customer counts nor model availability establishes annual chip shipments.
  31. NVIDIA Rubin architecture2026-07-21 · Two compute dies form one logical GPU; regularRubin288GB12Hi remains separate from unfinalizedUltra configurations.
  32. AMD MI450X specifications2026-11-12 · 288GB with8HBM stacks. Compare withMI455X432GB/12stacks; this is stack-count selection, not automatically an8Hi layer change.
  33. AMD MI455X specifications2026-07-23 · 432GB and12HBM stacks. Product choice is modeled at constant device count for the configuration bridge.
  34. TrendForce: Rubin Ultra configurations under evaluation2026-08-04 · Configuration and validation discussion predates the November CEO event. Does not confirm finalUltra architecture or adoption rate.
  35. TrendForce: HBM layer-count pricing2026-09-29 · 2027 forecast of8Hi10–20%per-Gb premium vs12Hi. Used as a constant-scope revenue sensitivity, not a2028 executed price.
  36. IEA Key Questions on Energy and AI, Table A.12026-04-16 · 2023/24/25IT capacity57/68/82GW initializes the historical stock. IEA2030 forecast is an external check, never an independent-model input. IT, facility rating, average load and annual energy differ.
  37. CBRE North America Data Center Trends H1 20262026-08-27 · Eight primaryNA markets: operating10.903GW,33.7%YoY; construction7.481GW. Selected-market scope cannot prove global25%growth.
  38. JLL North America Data Center Report Midyear 20262026-08-11 · 66GW under construction,95%precommitted. Construction and absorption are not commissioned power; do not add to narrowerCBRE coverage.
  39. Broadcom / financial partners: Anthropic financing structure2026-10-26 · 63bnUSDSPV transaction with committed financing, deliveries from2027. Broadcom residual-value support equals the first-lien portion; no claim all funds already drawn.
  40. NVIDIA AI compute financing platform memoranda2026-08-10 · MOU structure aiming to mobilize500bnUSDthird-party capital over time, subject to definitive agreements. Neither NVIDIAcash nor already funded GPU orders.
  41. SK hynix Q3 2026 results2026-10-28 · HBM4 ramp and M15X timing; more-than50%2027–28LTAcoverage concerns total capacity, not HBM-only volume.
  42. Samsung Q3 2026 earnings call2026-10-29 · 2027HBMallocation and agreed target prices; HBM4revenue mix is not wafer/bit mix. No published company-level HBMprofit floor.
  43. SK hynix / TSMC HBM4 cooperation2024-04-19 · Base-die and packaging cooperation; relationship existence does not establish annual customer allocation.
  44. NVIDIA FY2026 Form10-K: manufacturing and memory suppliers2026-02-25 · Names memory suppliers includingSKhynix,Micron,Samsung; generic supply relationship does not prove qualification for every generation.
  45. NVIDIA DGX Rubin NVL8 system specificationavailable2026-11-17 · 8GPUs and approximately24kW system power. System scope is distinct from acceleratorTDP and wholefacility capacity.
  46. Intel Foundry power-delivery white paper2026-08 · Original Intel analysis offers power-scaling estimates. Not an NVIDIA TDP disclosure; used only as engineering cross-check.
  47. Microsoft Maia multigigawatt deployment plan2026-10-12 · 96accelerators/167kWrack concernsMaia300. Do not attach this rack ratio toMaia200. Multi-GW deployment starts2027; annual mix is not disclosed.
  48. Anthropic / Google / Broadcom compute update2026-05-06 · 5GW agreement begins coming online2027. Calendar phasing is analyst-assumed; do not add the3.5GWsubset again.
  49. Core Scientific Q2 2026 Form 10-Q: AMD direct leases and Neocloud credit support2026-07-28 · Note 15 subsequent events: July 27 execution. AMD directly leases 377 MW; a separate Neocloud leases 152 MW under lease-specific AMD credit support, including equipment protections, optional cure rights and specified material-default provisions. The 1,925 MW reservation right is not included in contracted capacity. Filing date verified on the issuer IR filing page as July 28, not the June 30 period-end.
  50. NVIDIA Q3 FY2027 financial results2026-11-17 US / 2026-11-18 Beijing · Revenue, data-center revenue, Rubin shipments; Q4 guide includes an additional week and assumes no China Data Center compute revenue.
  51. NVIDIA Q3 FY2027 management earnings-call transcript2026-11-17 US / 2026-11-18 Beijing · Management speech transcribed by Quartr: FY2028 growth outlook, financing clarification, allocation, CPO, and capital priorities; third-party transcript of primary speech.
  52. NVIDIA Q3 FY2027 CFO Commentary2026-11-17 · Pages 2-5: China revenue; Oct25 supply commitments, Neocloud conditions and guarantees. These are pre-transition quarter-end balances. Furnished EX99.2, 8-K accession 0001045810-26-000088; 10-Q not yet filed.
  53. NVIDIA expands commitments with supply-chain partners2026-11-17 · Kinsus substrate expansion, Amkor prepayments, SPIL advanced packaging; announcement and planned ramp dates, not completed capacity.
  54. NVIDIA export-control oversight committee announcement2026-11-17 · Board-level national-security and export-control oversight; no assertion about new laws or license outcomes.
  55. NVIDIA introduces Nemotron for Science2026-11-16 · Post-transition product announcement; supports current activity in open scientific models, not a quantified long-term spending or sales guarantee.
版本1.4.0 · LunarTulip Research独立产业研究。模型假设与来源见附录;审阅由独立AI依基本面与数量框架执行。
Read the complete English edition

On November 12, Jensen Huang stepped down as NVIDIA CEO. His successor inherits a network linking chip supply, customer financing and data-center construction. NVIDIA sells GPUs to customers while helping some expand through capacity purchases and credit support. How much growth can that network sustain after the transition? The answer reaches Neocloud equipment purchases, HBM expansion returns and optical suppliers’ next orders.

The first test arrived with the November 17 results: NVIDIA guided to $130 billion next quarter, and management raised its FY2028 revenue-growth outlook from 70% to 75%. Following AlphaMap’s customer, supplier and credit relationships, we retain a near-term delivery-growth view. The expansion requiring the closest reassessment is Neocloud capacity still raising capital and the hosting leases attached to it. In networking, CPO adoption reallocates component value. Supply contracts prepare production; customer capital pays for equipment. The timing of both determines the next procurement cycle.

LunarTulip Research 01 · AlphaMap investment research · November 18, 2026

1. The first results after the transition put capital allocation at the center

NVIDIA supports growth on both sides of its business: it reserves future memory, wafer and packaging capacity, and helps selected customers secure infrastructure and compute services. Suppliers plan expansion against these arrangements; customers plan procurement. Capital allocation influences the pace of both.

Fiscal Q3 revenue reached $115.8 billion, including $107.6 billion from Data Center, and Rubin NVL72 began shipping. The $130 billion Q4 midpoint adds $14.2 billion, or 12.3%, to the quarter’s revenue. Q4 includes an extra week, so quarterly scale and weekly growth require separate treatment.[50]

Management raised its FY2028 growth outlook to 75% from 70%, incorporating customer capital and facility readiness into allocation decisions. We therefore retain delivery growth for projects with procurement and construction funding in place, and assess projects still raising capital against their payment calendars.[51]

The first AlphaMap hop identifies customers, suppliers and supported counterparties. The next reaches hosts, shared economic payers and alternative ASIC procurement. Those relationships connect the same event to different company cash flows.

Industry pathCurrent assessmentFinancial-model input
Neocloud and hostsFunded delivery continues; assess unfunded expansion project by projectDraws, equipment payments, acceptance and lease starts
HBM2027 contracts support delivery; 2028 expansion needs procurement fundingBits, prices, generation and inventory
Asian manufacturingAnnounced agreements support planned expansionPrepayments, ramps, qualified output
Optics and CPONetworking expands; component demand changes with architecturePorts, adoption, qualified supply value
China compute salesQ4 uses zero China Data Center compute revenueLicensing, region and alternative orders
Open modelsProduct investment continuesR&D, adoption and compute procurement
Figure 1 | Six research paths connect company arrangements with financial variables. Solid lines show disclosed relationships or guidance; dashed lines show analytical mechanisms.

Research judgments as of November 18, 2026. NVIDIA FY2028 and calendar-2028 HBM scenarios use different periods.

2. CoreWeave’s revenue support reaches its hosts through a payment calendar

NVIDIA’s specified residual-capacity purchase agreement with CoreWeave had an initial value of $6.3 billion and runs through April 2032. NVIDIA buys eligible residual capacity after contractual delivery and service conditions are met. That arrangement supports specified future receipts, a source operators can present to lenders.[2]

Construction precedes operating receipts. CoreWeave generated $5.638 billion of operating cash flow in the first nine months and spent $23.558 billion on cash PP&E and software, a 23.9% coverage ratio. Net financing of $21.346 billion funded much of the expansion. Management expected $9 billion of customer prepayments and deposits over the following three months; receipt timing affects the next equipment-payment window.[3][5]

Our illustrative payment stress delays 20% of the $9 billion, reducing near-term receipts by $1.8 billion. With $1 billion of immediately available substitute capital, $800 million requires further financing or payment extension. Sufficient borrowing preserves procurement while interest reduces equity cash. Each additional 100 basis points on $1 billion adds $10 million of annual interest. Readers can replace these assumptions.[3][5]

The new CFO commentary clarifies sequencing: Neoclouds secure purchase financing, deploy and operate capacity, then obtain acceptance before the relevant support takes effect. In Q&A, management said this mechanism was already in place. We retain project-by-project funding and procurement assessments, anchored to capital available at payment dates.[51][52]

Figure 2 | The case network: 13 existing AlphaMap relationships and nine public-source supplements. New manufacturing evidence is documented separately.

3. CORZ is diversifying contracted capacity; current receipts remain concentrated

One hop beyond CoreWeave reaches Core Scientific (CORZ). At September-end, all colocation revenue came from CoreWeave, which represented approximately 84% of group nine-month revenue. Of CoreWeave’s 590 MW, 485 MW was billable, or 82%. Billing the remaining 105 MW affects incremental hosting revenue.[6][7]

Future contracts add 377 MW leased directly by AMD and 152 MW leased by another Neocloud with specified conditional AMD credit support. CoreWeave represents about 53% of the combined approximately 1,120 MW. The newer leases had yet to commence; customer diversification reaches revenue as the expected 2027–2028 deliveries enter service.[6][7][49]

Our near-term CORZ cash-flow assessment therefore remains centered on CoreWeave’s payment and credit terms. Revenue from the additional 529 MW follows each lease’s financing, construction and commencement. For an eligible lease at the 50% credit cap, $100 of eligible monthly fees produces $50 of current receipts. With the fee held constant, receipts rise to $100 after credits expire. Project debt terms then govern interest, amortization and reserves.[7][8]

Other sponsors create alternative buildout paths. Google supports specified Akela leases; Broadcom participates in the $63 billion equipment-SPV financing arrangement connected to Anthropic XPU and networking purchases. We retain the instrument and closing conditions for each contract and assess GPU and ASIC procurement alongside one another.[11][39]

Figure 3 | CORZ: current revenue concentration, future contracted IT and CoreWeave billable capacity use distinct denominators.

4. Memory and packaging have supply arrangements; incremental demand needs a payer

At October 25, supply and capacity commitments rose from $279 billion to $390 billion, a $111 billion increase, or 39.8%, primarily for multiyear memory procurement. These pre-transition arrangements support suppliers’ capacity planning. We separately track supply commitments that prepare production and customer financing that pays for equipment.[52]

The November 17 supply-chain announcement extends across Asian substrates and packaging. Kinsus plans to expand dedicated NVIDIA ABF capacity “by more than 3.5x over current levels,” targeting additional capacity in Q3 2028. Amkor’s previously announced agreements totaling nearly $3 billion include prepayments. NVIDIA’s multibillion-dollar support for SPIL targets expanded dedicated advanced packaging by mid-2029.[53]

We retain a contract-supported 2027 HBM delivery view. Micron said agreements cover the vast majority of calendar-2027 HBM bits with significant year-over-year pricing increases. Qualified output, buyer volumes and transaction prices determine the return on 2028 expansion.[20]

Our independent supply model applies annual wafer processing, effective output and generation mix to estimate 7.83 EB of initial-mix 2028 capability from the three major suppliers, with engineering scenarios of 5.89–10.28 EB. The full desired-device path uses about 11.10 EB; ASICs contribute approximately 75% of incremental device units from 2026 to 2028. Customer mix and qualified generations shape absorption.[25][26][27][28]

We first assess HBM supply with agreed pricing, volumes and customer qualification, then evaluate additional lines. Actual purchase prices and allocated capacity inform NVIDIA’s sourcing position; procurement funding across both GPU and ASIC customers informs industry demand.

Figure 4 | Top-three initial-mix HBM capability and matched covered-device procurement. Engineering scenarios vary wafer ramps, allocation and recovery.

5. The 2028 HBM procurement difference needs buyers to finance inventory

Buyers fund equipment between procurement and commissioning. Holding facility-IT growth at 25%, mid-case device power, opening inventory and a one-quarter physical lag constant, we compare procurement one, two and four quarters ahead. Covered-device HBM in 2028 is 4.958, 5.212 and 7.311 EB respectively; year-end installed AI-system IT is 99.7 GW in all three cases.[36]

Moving procurement from one quarter to one year ahead adds 2.354 EB, or 47.5%, to annual purchases and 4.433 EB to year-end uninstalled-device HBM. Assuming $30,000 per GPU and $10,000 per ASIC, the longer policy ties up another $217.4 billion of year-end accelerator capital. Buying early converts future installations into current orders and puts the inventory capital on the buyer’s balance sheet.

The calculation identifies the funding scale behind distant HBM growth. IREN’s financing for its Microsoft project draws in tranches against delivery milestones and conditions. Such structures link receipt schedules to milestones. Customer advances, drawable facilities and equipment-payment dates therefore belong in procurement analysis.[14][15]

Configuration changes are a separate experiment. Holding the same 2028 device cohort constant, the applicable Ultra engineering configurations and MI450X/MI455X selection reduce HBM from 11.42 to 11.10 EB, or about 0.32 EB and 2.8%. The fixed-device experiment measures configuration; the procurement-window experiment measures inventory timing and capital. Each informs supplier absorption through its own mechanism.[31][32][33][34]

Figure 5 | Procurement policy sensitivity at the same assumed installation path. Annual flow differs by 2.354 EB; year-end uninstalled HBM differs by 4.433 EB.

Test the same thesis under different conditions

Annual device-embedded HBM4.958EB · 2028
Of which, matched Top3 absorption4.909EB · 2028
Year-end uninstalled embedded HBM1.334EB · 2028
Year-end installed AI-system IT99.7GW · 2028

All 27 combinations are full runs of the frozen model; no front-end interpolation. Memory/area are fixed at mid values and physical lag at one quarter. The 25% facility path is accelerated. Outputs cover the modeled devices and do not carry calibrated industry probabilities.

6. CPO enters production networks; optics needs a per-port value model

The call reported CPO operating in production networks. Management disclosed more than $21 billion of quarterly networking revenue, volume production of CPO scale-out, and Lambda’s first production deployment connecting more than 10,000 GB300 GPUs. We retain a networking-buildout view and bring component substitution into optical suppliers’ revenue assumptions.[51]

For the same set of scale-out optical connections that can use either CPO or pluggable solutions, supplier revenue equals delivered ports × architecture adoption × qualified share × supply value per port. Cluster expansion and rising CPO adoption can produce different order growth for the two architectures.

Our normalized example increases that comparable set of delivered ports by 50% and raises CPO share from 10% to 30%, holding share and per-port value constant. Pluggable-related ports rise by 1.5 × 70% / 90% − 1 = 16.7%; CPO ports rise by 1.5 × 30% / 10% − 1 = 350%. Company revenue follows its actual component perimeter, qualification and pricing.

We remain constructive on network infrastructure activity and separately estimate pluggable modules, optical engines and other supplied components. Continued CPO adoption allocates part of incremental interconnect value to qualified suppliers.

Normalized sensitivity for the same substitutable scale-out connections. Port growth and adoption shares are explicit assumptions.

7. China sales and open models enter different parts of the demand model

The new guide incorporates China. Quarterly Hopper Data Center sales to China were $2.4 billion; Q4 assumes zero China Data Center compute revenue. Subtracting the $2.4 billion produces a $113.4 billion comparison base. The $130 billion guide midpoint is $16.6 billion, or 14.6%, above that base. Other sales and products carry the next quarter’s expected expansion.[50][52]

We use zero China Data Center compute sales in the next-quarter view and track overseas orders, product mix and delivery dates separately. The board also established a national-security and export-control oversight committee; licenses and regional channels remain company-specific update variables.[54]

The open ecosystem continues through product activity. On November 16 NVIDIA introduced Nemotron for Science, extending open models into scientific workflows. Our inference is that deployable models can broaden GPU use cases; developer adoption, service workloads and procurement test that demand path.[55]

Separating these mechanisms preserves their economic meaning: export eligibility and orders determine regional compute sales, while model adoption influences compute use. Each modifies its own input, with common end workloads reconciled across paths.

Figure 6 | Quarterly scale: $115.8bn less $2.4bn China Hopper sales gives a $113.4bn comparison base, versus the $130bn Q4 midpoint. Q4 includes an extra week.

Investment view: near-term growth continues; funding and component mix shape the next cycle

At the first earnings checkpoint after the transition, we retain a near-term NVIDIA delivery-growth view, contract-supported HBM deliveries and continued network infrastructure deployment. New guidance, signed supply arrangements and production activity support those judgments respectively.

We assess funded projects against contractual delivery and revenue timing; for expansion dependent on external capital, we reconcile available amounts with equipment-payment dates. CoreWeave receipts connect to CORZ lease commencement and collections; additional HBM capacity connects to customers’ inventory capital; optical revenue connects to CPO component value. These inputs distinguish realized company growth within the same AI spending cycle.

Updates replace specific inputs: actual drawings and advances revise equipment-payment schedules by amount, use and date; acceptance and lease commencement revise hosting revenue; generation qualification and pricing agreements revise HBM absorption; disclosed CPO ports and supplied components revise optical-product revenue.

This is AlphaMap’s contribution in the case: start with a company, identify shared payers, support instruments and second-hop suppliers, then connect each material relationship to a financial assumption. Existing relationships and public supplements retain provenance so readers can follow contracts into inputs, reproduce the arithmetic and form their own investment view.

LUNARTULIP RESEARCH

LunarTulip Research examines how industry changes reach company cash flows through customers, contracts and capital expenditure. This study starts from AlphaMap relationships, adds verified public evidence and independent calculations, and brings financing support, shared customers and alternative procurement into the same investment assessment.

Bring a company you cover and an investment question about shared customers, capacity delivery or financing dependence.

Model, evidence and reproducible appendices

Update and model identity

This edition updates company assessments using disclosures available on November 18 Beijing time. HBM quantities retain independent model 4.1. FY2028 growth is management guidance; calendar-2028 devices, facility growth, procurement policies and future BOMs are separately identified research assumptions.

The model covers high-end cloud accelerators. Top-three initial-mix capability is 7.83 EB in 2028; one-, two- and four-quarter policies produce 4.958, 5.212 and 7.311 EB of covered-device embedded HBM. Other buyers and raw-memory/WIP inventory affect supplier shipments. The globally calibrated procurement path and same-scope adjudication of the separate November 17 external revisions remain open in the research ledger.

The CPO illustration uses delivered ports within the same substitutable scale-out connection set. Kinsus expansion retains the announcement’s wording; it is not converted into wafer or chip output.

Update and model identity

This edition updates company assessments using disclosures available on November 18 Beijing time. HBM quantities retain independent model 4.1. FY2028 growth is management guidance; calendar-2028 devices, facility growth, procurement policies and future BOMs are separately identified research assumptions.

The model covers high-end cloud accelerators. Top-three initial-mix capability is 7.83 EB in 2028; one-, two- and four-quarter policies produce 4.958, 5.212 and 7.311 EB of covered-device embedded HBM. Other buyers and raw-memory/WIP inventory affect supplier shipments. The globally calibrated procurement path and same-scope adjudication of the separate November 17 external revisions remain open in the research ledger.

The CPO illustration uses delivered ports within the same substitutable scale-out connection set. Kinsus expansion retains the announcement’s wording; it is not converted into wafer or chip output.

Update and model identity

This edition updates company assessments using disclosures available on November 18 Beijing time. HBM quantities retain independent model 4.1. FY2028 growth is management guidance; calendar-2028 devices, facility growth, procurement policies and future BOMs are separately identified research assumptions.

The model covers high-end cloud accelerators. Top-three initial-mix capability is 7.83 EB in 2028; one-, two- and four-quarter policies produce 4.958, 5.212 and 7.311 EB of covered-device embedded HBM. Other buyers and raw-memory/WIP inventory affect supplier shipments. The globally calibrated procurement path and same-scope adjudication of the separate November 17 external revisions remain open in the research ledger.

The CPO illustration uses delivered ports within the same substitutable scale-out connection set. Kinsus expansion retains the announcement’s wording; it is not converted into wafer or chip output.

Update and model identity

This edition updates company assessments using disclosures available on November 18 Beijing time. HBM quantities retain independent model 4.1. FY2028 growth is management guidance; calendar-2028 devices, facility growth, procurement policies and future BOMs are separately identified research assumptions.

The model covers high-end cloud accelerators. Top-three initial-mix capability is 7.83 EB in 2028; one-, two- and four-quarter policies produce 4.958, 5.212 and 7.311 EB of covered-device embedded HBM. Other buyers and raw-memory/WIP inventory affect supplier shipments. The globally calibrated procurement path and same-scope adjudication of the separate November 17 external revisions remain open in the research ledger.

The CPO illustration uses delivered ports within the same substitutable scale-out connection set. Kinsus expansion retains the announcement’s wording; it is not converted into wafer or chip output.

Update and model identity

This edition updates company assessments using disclosures available on November 18 Beijing time. HBM quantities retain independent model 4.1. FY2028 growth is management guidance; calendar-2028 devices, facility growth, procurement policies and future BOMs are separately identified research assumptions.

The model covers high-end cloud accelerators. Top-three initial-mix capability is 7.83 EB in 2028; one-, two- and four-quarter policies produce 4.958, 5.212 and 7.311 EB of covered-device embedded HBM. Other buyers and raw-memory/WIP inventory affect supplier shipments. The globally calibrated procurement path and same-scope adjudication of the separate November 17 external revisions remain open in the research ledger.

The CPO illustration uses delivered ports within the same substitutable scale-out connection set. Kinsus expansion retains the announcement’s wording; it is not converted into wafer or chip output.

Update and model identity

This edition updates company assessments using disclosures available on November 18 Beijing time. HBM quantities retain independent model 4.1. FY2028 growth is management guidance; calendar-2028 devices, facility growth, procurement policies and future BOMs are separately identified research assumptions.

The model covers high-end cloud accelerators. Top-three initial-mix capability is 7.83 EB in 2028; one-, two- and four-quarter policies produce 4.958, 5.212 and 7.311 EB of covered-device embedded HBM. Other buyers and raw-memory/WIP inventory affect supplier shipments. The globally calibrated procurement path and same-scope adjudication of the separate November 17 external revisions remain open in the research ledger.

The CPO illustration uses delivered ports within the same substitutable scale-out connection set. Kinsus expansion retains the announcement’s wording; it is not converted into wafer or chip output.

The appendices distinguish disclosures, external estimates and our assumptions. Model 4.1 is frozen. One-, two- and four-quarter procurement policies are shown together without uncalibrated probabilities.

A | From devices and wafers to inventory and cash
StageCalculation and unitInput status
DemandBuyer/platform quantities × product mix → annual SKU demandEstimated 2026 reference; forward growth, buyer phasing and mix are assumptions [28][29][48]
HBM supplyΣ wafers × geometric dies/wafer × Gb/die ÷ 8 × effective qualified recovery ÷ 10⁹ → nominal EBIssuer construction plans, original research estimates and explicit ramp/recovery assumptions [20][25][26][27]
MatchingGeneration-compatible supply subject to wafer budgets and BOMs; planned reallocation requires qualificationRecovery already includes qualification. Maximum capacity is not automatically produced.
Procurement / installationQuarterly purchases − installations = uninstalled inventory change; installed stock = prior stock + installations − retirements1/2/4-quarter procurement lookahead is distinct from one-quarter physical lag. Opening inventory is fixed; cohorts retain SKU and origin.
Logic areaΣ million devices × mm²/device → good logic m²Compute, I/O and active logic layers; excludes HBM, interposer and substrate. Not wafer-start area.
PowerRated annual equipment-flow GW → installed system IT GW → load/PUE-adjusted TWhAnnual shipments, year-end stock, average facility load and annual electricity are separate.
Revenue / tied-up capitalBits × relevant price; inventory devices × relevant costRevenue recognition, raw-HBM/WIP changes and actual purchase prices require their own bridges. Costs here are scenario scales.

Nominal GB/EB conventions are applied consistently on both sides. The model does not convert one side from GiB to decimal GB while leaving the other unchanged. Two Blackwell/Rubin compute dies still form one GPU; TPU8i Max contains two underlying devices per package without doubling per-device memory. [30][31]

B | Assumptions that determine the result
ParameterBase and rangeBasis / consequential boundary
2025 IT stock82 GW global; 25 GW AI / 57 GW conventional82 GW is IEA’s estimate; the split is our assumption [36]
Facility growth20% / 25% / 30% annual global IT growth25% is accelerated: ~250 GW in 2030 versus IEA’s external 174 GW forecast. No IEA 2030 forecast is an input [36][37][38]
AI readiness / geography100% of available incremental IT in base; 85% sensitivityPower, cooling, network and location must all match. Global fungibility is an optimistic boundary.
System overhead / energySystem IT/rated accelerator power 1.45; range 1.25–1.65; new-AI load 0.60 and PUE 1.15PUE affects energy, not installable IT capacity. System/rack ratings are not chip TDP [23][45][46]
Opening stock / life5.672 GW uninstalled; 50% H200 / 50% B200 device-count proxy; new life five yearsNot observed inventory. Opening state is identical across policies; legacy AI retires evenly over five years.
Procurement1/2/4 quarters ahead; one-quarter physical readiness lagInstallation lag is not a unique purchasing rule. Ready equipment can wait in inventory.
Future BOMConstant 24 Gb in base; future 480 GB is a 50/50 population of 384/576 GB configurationsNot an announced 480 GB SKU or 10-Hi product. Forced 32 Gb transition is a separate stress.
Memory inventoryZero net raw-HBM/WIP inventory change in baseDevice-embedded memory can proxy covered-device absorption, not total market shipments or revenue.
Constraints not solved separatelyLogic front-end, CoWoS, substrates and board throughputA complete process/customer global capacity panel is not available; logic area is a derived demand mapping.
2029–2030Explicit continuation paths for capacity, products and procurement into 2031Greater long-horizon uncertainty; annual outputs are not validated whole-market point forecasts.
C | Desired-device path and 2028 configurations
YearNVIDIA GPUOther GPUGoogle TPUOther ASICTotal / m devicesASIC share
20267.700.843.423.8115.7845.9%
20279.231.436.336.4823.4854.6%
202810.162.018.869.0830.1159.6%
202910.672.5111.0811.3535.6063.0%
203010.673.0113.3013.6240.5966.3%

This is desired demand before supply, financing and facility constraints, not observed orders. The 2026 reference is backcast from a 2027 public research abstract and growth rates, so it remains an estimate. At constant prices and GPU/ASIC cost ratio 3:1, the 2028 equipment budget must rise 65.7% from 2026. Unit-cost or owned/leased changes require updating the budget bridge. [28]

Named customer programmes explain only part of growth. AWS’s additional two million GPUs are phased over their disclosed delivery interval; Anthropic’s 5 GW is not all Google TPU demand. Residual customer growth remains an assumption. Total hyperscaler capex is not divided by a GPU price. [29][48]

2028 product / populationDemand / mNominal GB/deviceRated W/deviceLogic mm²/devicePower basis
B300 HGX0.12228811001650Disclosed power anchor
GB300 NVL72 GPU portion0.18328814001650Disclosed power anchor
Rubin GPU1.91028818001650Engineering power
Rubin Ultra architecture branches2.86548028003300Engineering power
Post-2027 GPU family (unnamed)5.07948032003300Engineering power
MI450X0.30128818002870Engineering power
MI455X0.50243218002870Engineering power
Post-MI400 GPU family (unnamed)1.20548024003200Engineering power
TPU8t1.33021612001550Engineering power
TPU8i2.21628813001550Engineering power
Future TPU family (unnamed)5.31938416001900Engineering power
Trainium30.9081448001100Engineering power
Trainium4 and successor family4.53928813001600Engineering power
MTIA400/4500.45438414002300Engineering power
MTIA500 and successor family1.81548022003600Engineering power
Maia2000.454216900800Disclosed power anchor
Unspecified HBM ASIC family0.90824012001500Engineering power

Future configurations, adoption and most power/area values are engineering estimates, not vendor shipment guidance. The package includes low/mid/high BOMs, generation joins and the 79-row annual device panel.

D | HBM capacity, source disagreement and reallocation
SupplierAverage capacity / kwpmAnnual wafers / mEffective recoveryNominal GB/waferCapacity / EB
Samsung2803.3662%9113.062
SK hynix3003.6069%10173.662
Micron1001.2062%9261.111

Average capacity is matched front-/back-end capability. Effective recovery includes yield, assembly/test and qualification losses; another blanket qualification discount would double count. 2028 fab allocation and recovery are our assumptions, not a complete issuer-disclosed generation-output matrix. [20][25][26][27]

External researchDate / original estimateTreatment here
LSNov 16: SK hynix 2027 ~2.779 EBSK absolute-output calibration; broker estimate, not issuer actual [25]
HanaNov 12: 2027 Samsung/SK/Micron 2.0/2.3/0.6 EBThe 4.9 EB total remains an external conflict/low-case reference. SK 2.3 and 2.779 are not silently averaged [26]
Our 2028Fixed recipe 7.8348 EB; planned reallocation 7.9407 EBReallocation adds 0.1059 EB within the same wafer budget. Adding 0.0787 EB outside-pool memory yields an 8.0194 EB covered-device ceiling.

Reallocation requires process planning, qualification and matching back-end capacity. It is a feasible capacity solution. Under one-quarter procurement, matched absorption is 4.9089 EB and total device-embedded memory is 4.9575 EB. Unused capacity does not automatically become inventory or revenue. “Semi” in the Hana filename means semiconductor; it is not SemiAnalysis.

E | Annual physical outputs, 2026–2030

One-quarter procurement

YearManufactured / mEmbedded HBM / EBLogic / 000 m²Rated flow / GWYear-end AI IT / GWAll DC / TWh
202615.343.49422.3117.2644.27545
202714.884.09825.9521.6768.82683
202813.454.95830.9025.9899.67860
202915.496.09537.5631.81138.501075
203020.748.19350.0042.14187.311346

Four-quarter procurement

YearManufactured / mEmbedded HBM / EBLogic / 000 m²Rated flow / GWYear-end AI IT / GWAll DC / TWh
202615.783.59222.9317.7544.36545
202722.036.06738.4232.0868.82684
202819.837.31145.5838.3299.67860
202918.077.11243.8337.11138.501075
203029.0711.48670.0959.08187.311346

Both tables hold 25% facility growth, mid power, one-quarter physical lag and opening inventory fixed. The one-quarter policy produces ~166,719 m² cumulative logic area in 2026–2030. Its 2030 rated equipment flow of 42.14 GW, installed AI IT of 187.31 GW, all-DC IT of 250.24 GW and 1,346 TWh answer different questions; a single 34% comparison cannot be applied to all of them.

IEA’s external 2030 forecast is approximately 174 GW of all-DC IT, 226 GW rated facility capacity and 945 TWh. Our accelerated path is not reverse-fitted to those forecasts. Lower growth paths can be checked directly. Unannounced products and continuing HBM process/capacity assumptions materially affect 2029–2030. [36]

F | Inventory and financing: flows do not replace stocks
Lookahead / qAnnual embedded / EBUninstalled / mInventory HBM / EBInventory IT / GWInstalled AI IT / GW
14.95753.6181.33410.13899.667
25.21247.4242.73720.80299.667
47.311115.6435.76743.82999.667

Four quarters versus one adds 2.3536 EB of annual procurement, but 4.4331 EB and 12.0244 million devices to year-end inventory. Flow and stock are not interchangeable. Equal commissioned GW also does not require identical installed device cohorts or HBM.

Assumed ASIC priceAssumed GPU priceExtra year-end accelerator capital / $bn
$5,000$15,000108.7
$10,000$30,000217.4
$15,000$45,000326.1

Prices are normalised assumptions at GPU:ASIC=3:1. Extra inventory is approximately 4.8588 million GPUs and 7.1656 million ASICs. Tied-up capital is not annual incremental capex, committed financing, net debt or market-value impact.

G | Company financial transmission and falsifiers
Company / relationshipFinancial exposureTransmission gate and evidence
Samsung / Micron2027 delivery/pricing; returns on 2028 expansionNegotiated volume/pricing improve visibility; cancellation, delivery and inventories still matter [20][42]
NVIDIA → CoreWeaveEquipment/service delivery, funding costs and capex timingSpecified residual-capacity purchases have performance conditions; not a guarantee of all company debt [2]
AMD / unnamed Neocloud → CORZFuture customer mix, construction financing and lease start377 MW AMD direct leases plus 152 MW third-party leases; specified conditional AMD support applies to the latter. Neither group had commenced at September-end; current colocation revenue was still 100% CoreWeave. 590/(590+530), about 53%, is a future capacity share [6][7][49]
CoreWeave → APLD / CORZConstruction spend, lease start, cash receipts and debt coverageProject funding, acceptance, billing and advance credits; a customer’s stock decline does not automatically reduce rent [6][7][9][10]
Microsoft → CRWV / NBIS / IRENCommon budget, delivery and collection concentrationDeduplicate overlapping capacity/workloads only. IREN’s Microsoft DDTL has four tranches and conditions precedent [3][12][13][14]
Google → Akela / FluidstackLease credit risk, protection and WULF dilutionLease/default conditions and termination-fee/assumption choice; not blanket construction protection [11]
Broadcom → SPV → AnthropicASIC delivery, equipment leasing and residual supportThe $63bn financing commitment does not establish that the full amount has been drawn. Broadcom’s support equals first-lien loans, not an unconditional guarantee of the entire sum [39]
NVIDIA → SB Energy / OpenAIConditional project support and future support choices4.25 GW IT / nine phases / $105bn guarantee cap; lease-start and specified-default triggers. Another 3.8 GW is discretionary [19]

The incremental leadership effect requires new orders, amendments, support choices or changed financing terms. No unsupported global cancellation haircut enters the base; this does not prove a zero event effect. Prior power delays or Q3 refundability changes cannot be attributed to November 12. [1][3][19]

ChannelObservable evidenceInference limit
ExpectationsEarnings estimates, financing quotes, valuations and event timesCo-declines do not establish contractual cash loss
FinancingCollected advances, restricted cash, drawability, alternatives and payment calendarCommitments are not spendable cash
OperationsDelivery/acceptance, lease start, credits and collectionsCount a root event once across paths; no short-return backtest is claimed
H | Distinct identities of the two SemiAnalysis materials
MaterialAvailable informationTreatment
Older Nov13 vs Nov2 charts [16]2028 HBM 9.0→6.4 EB; displayed 2026–30 area series; 2030 power 122.8→80.7 GWOld displayed-value arithmetic only. Power scope pending; not a baseline for the newer report.
Separate Nov17 report [18]Separately supplied headline: cumulative area −17%, 2028 HBM −30%, 2030 power −34%Verifiable original, levels and previous baseline not obtained; identity remains distinct.
Our frozen model2028 capacity ~7.8 EB; policy procurement 5.0/5.2/7.3 EB; constant-device configuration change 2.8%No external revision/baseline input. Exact-magnitude adjudication remains incomplete pending a common perimeter.

A forecast cut is relative to an earlier forecast, not necessarily a year-on-year decline. GPU share loss, ASIC growth, lower memory per device and power-efficiency changes can coexist with different magnitudes. Absolute levels and driver decompositions require separate comparison.

I | Retained project cash and debt exhibits

This appendix retains the previously verified cash/contract modules: CoreWeave cash coverage and Core Scientific billing, advance credits and a specific debt schedule. They explain company differences without replacing a global hardware model.

01 crwv cash investment
02 corz billing
03 corz credit mechanism
04 corz debt service

The CORZ debt illustration uses a 7.75% coupon, $3.3bn principal and initial annual amortisation of 11.5%. The assumed first instalment on November 15, 2029 depends on relevant lease commencement, credit exhaustion and a qualifying payment date. It is not a complete company free-cash-flow forecast. [7][8]

J | Relationship-to-source mapping
FromRelationshipToProvenance
NVIDIAGPU supplyCoreWeaveExisting AlphaMap [3]
CoreWeaveCompute serviceMicrosoftExisting AlphaMap [3]
CoreWeaveCompute serviceOpenAIExisting AlphaMap [3]
NebiusPhased GPU serviceMicrosoftExisting AlphaMap [12][13]
IRENPhased GPU serviceMicrosoftExisting AlphaMap [14][15]
Applied DigitalProject hostingCoreWeaveExisting AlphaMap [9][10]
TeraWulfIndirect subsidiaryAkelaExisting AlphaMap [11]
AkelaProject leasesFluidstackExisting AlphaMap [11]
GoogleConditional credit supportAkelaExisting AlphaMap [11]
TeraWulfWarrant considerationGoogleExisting AlphaMap [11]
NVIDIAConditional residual-capacity purchaseCoreWeavePublic supplement [2]
Core ScientificProject hostingCoreWeavePublic supplement [6][7][8]
IRENCloud-services customer contractNVIDIAPublic supplement [14]
SK hynixMemory supplyNVIDIAExisting AlphaMap [44]
MicronMemory supplyNVIDIAExisting AlphaMap [44]
SK hynixHBM4 base-die cooperationTSMCExisting AlphaMap [43]
BroadcomResidual support = first lienFinancing SPVPublic supplement [39]
BroadcomXPU / networking supplyFinancing SPVPublic supplement [39]
Financing SPVEquipment leasingAnthropicPublic supplement [39]
Core Scientific377 MW direct lease / pendingAMDPublic supplement [6][7][49]
Core Scientific152 MW lease / pendingUndisclosed NeocloudPublic supplement [6][7][49]
AMDConditional support: 152 MW onlyCore ScientificPublic supplement [49]

Thirteen existing relationships guide discovery, with nine public supplements for current contracts and supply structure. Arrows represent service, goods, ownership or support, not a universal cash direction. Path counts do not generate return correlations or probabilities. No production AlphaMap write is claimed.

Sources and definitions

  1. NVIDIA CEO transition2026-11-12 · Corporate announcement
  2. CoreWeave: NVIDIA capacity-purchase arrangement2025-09-15 · Form 8-K; specified residual capacity, through April 13, 2032
  3. CoreWeave Q3 2026 Form 10-Q2026-11-10 · Cash-flow statement: nine months ended September 30, 2026; named customers
  4. CoreWeave Q3 2026 results2026-11-10 · Results release
  5. CoreWeave Q3 2026 earnings call2026-11-10 · PDF pages 2 and 6; expected customer prepayments/deposits, not receipts
  6. Core Scientific Q3 2026 presentation2026-11-05 · Slides 4, 6, 9–13; leased and billable IT capacity, AMD-associated delivery expectations, CoreWeave contract book and construction credits
  7. Core Scientific Q3 2026 Form 10-Q2026-11-05 · Notes 6–7 and MD&A; uncommenced AMD-associated leases, current CoreWeave customer concentration, construction financing and contingent debt schedule
  8. Core Scientific Finance I LLC indenture2026-05-06 · Sections 4.23 and 14.01; principal and cash-use conditions
  9. Applied Digital Q1 FY2027 results2026-10-07 · Polaris Forge 1 delivery and completed project-note issuance
  10. Applied Digital FY2026 Form 10-K2026-07-29 · CoreWeave hosting scope and legal entities
  11. TeraWulf Q3 2026 Form 10-Q2026-11-06 · Akela/Fluidstack leases, Google recognition agreements and warrants
  12. Nebius Q3 2026 shareholder letter2026-11-12 · Microsoft NJ deployment schedule; companywide funding expectations
  13. Nebius Microsoft agreement summary2025-09-08 · Form 6-K; financing, phased delivery, grace period and alternative capacity
  14. IREN FY2026 Form 10-K2026-08-27 · Microsoft tranche prepayment/credit terms; NVIDIA cloud-services contract
  15. IREN Q1 FY2027 results2026-11-05 · Horizon rollout; scope and conditions of funding statements
  16. SemiAnalysis Accelerator Model: supplied comparison charts2026-11-13 model / 2026-11-02 previous version · Displayed chart values supplied to LunarTulip; circulated November 17. Original institutional report and underlying Excel not obtained. Calculations use displayed rounded values, not independently calibrated forecasts.
  17. SemiAnalysis Accelerator & HBM Model: official methodologyAccessed 2026-11-17 · Official model methodology and scope, not the underlying data for this revision
  18. Separate SemiAnalysis November 17 report: user-supplied headline summary2026-11-17, identified by user; original pending · Distinct from source 16. User reports -17% cumulative 2026–2030 accelerator logic area, -30% 2028 HBM, -34% 2030 data-centre power. Original text, baseline, metric perimeter and model inputs not yet obtained. No original-report audit claimed.
  19. NVIDIA Q2 FY2027 commitments and guarantees2026-08-26 filing; July 26 balances and August subsequent event · AI cloud service agreements, SB Energy/OpenAI conditional guarantees and optional further support; fiscal years
  20. Micron Q4 FY2026 prepared remarks2026-09-30 · Industry DRAM bit outlook, contracted 2027 HBM and capex-to-output lag; company expectations
  21. Microsoft FY2027 Q1 earnings call2026-10-28 · Customer demand, capital spending and third-party delivery timing; company CapEx includes finance leases
  22. Alphabet Q3 2026 earnings call2026-10-28 · 2026 cash capital spending guidance; server/network versus building mix; company outlook
  23. NVIDIA DGX B300 specificationsAccessed 2026-11-17 · Eight GPUs, reported 2.1 TB GPU memory, approximately 14 kW system power; hardware-equivalent illustration
  24. CoreWeave Vera Rubin MLPerf announcement2026-11-16 · Post-transition execution evidence in Available category; not a funding or all-roadmap guarantee
  25. LS Securities: SK hynix forecast and quarterly TSV model2026-11-16 · Original broker estimates, PDF p3. 2026/27 HBM2.117/2.779 nominalEB and annual processing2.205/2.85m wafers. Estimates, not issuer-reported actual output.
  26. Hana Securities: semiconductor industry capacity study2026-11-12 · Original broker estimates, printed p25. Supplier capacity paths and new-DRAM-fab scale. Filename Semi means semiconductor, not SemiAnalysis. Capacity timing and HBM allocation are modeled separately.
  27. Samsung Securities: HBM wafer geometry2026-06-02 · Printed p19 engineering estimates for dies per wafer and effective recovery; not measured factory yields.
  28. DIGITIMES: high-end cloud AI accelerator shipments2026-10-19 · Public original-publisher abstract anchors a backcast2026 estimate. Full paid report/count dictionary not accessed; 2026 is not an observed actual. Our forward growth assumptions are separate.
  29. NVIDIA Q2 FY2027 earnings call2026-08-26 · AWS additional2mGPUs over the stated multi-year period; no calendar-year delivery schedule. Revenue opportunity perGW includes multiple products, not a GPU ASP.
  30. Google TPU8t and TPU8i technical deep dive2026-04-22 · Official capacity/specification definitions. Neither customer counts nor model availability establishes annual chip shipments.
  31. NVIDIA Rubin architecture2026-07-21 · Two compute dies form one logical GPU; regularRubin288GB12Hi remains separate from unfinalizedUltra configurations.
  32. AMD MI450X specifications2026-11-12 · 288GB with8HBM stacks. Compare withMI455X432GB/12stacks; this is stack-count selection, not automatically an8Hi layer change.
  33. AMD MI455X specifications2026-07-23 · 432GB and12HBM stacks. Product choice is modeled at constant device count for the configuration bridge.
  34. TrendForce: Rubin Ultra configurations under evaluation2026-08-04 · Configuration and validation discussion predates the November CEO event. Does not confirm finalUltra architecture or adoption rate.
  35. TrendForce: HBM layer-count pricing2026-09-29 · 2027 forecast of8Hi10–20%per-Gb premium vs12Hi. Used as a constant-scope revenue sensitivity, not a2028 executed price.
  36. IEA Key Questions on Energy and AI, Table A.12026-04-16 · 2023/24/25IT capacity57/68/82GW initializes the historical stock. IEA2030 forecast is an external check, never an independent-model input. IT, facility rating, average load and annual energy differ.
  37. CBRE North America Data Center Trends H1 20262026-08-27 · Eight primaryNA markets: operating10.903GW,33.7%YoY; construction7.481GW. Selected-market scope cannot prove global25%growth.
  38. JLL North America Data Center Report Midyear 20262026-08-11 · 66GW under construction,95%precommitted. Construction and absorption are not commissioned power; do not add to narrowerCBRE coverage.
  39. Broadcom / financial partners: Anthropic financing structure2026-10-26 · 63bnUSDSPV transaction with committed financing, deliveries from2027. Broadcom residual-value support equals the first-lien portion; no claim all funds already drawn.
  40. NVIDIA AI compute financing platform memoranda2026-08-10 · MOU structure aiming to mobilize500bnUSDthird-party capital over time, subject to definitive agreements. Neither NVIDIAcash nor already funded GPU orders.
  41. SK hynix Q3 2026 results2026-10-28 · HBM4 ramp and M15X timing; more-than50%2027–28LTAcoverage concerns total capacity, not HBM-only volume.
  42. Samsung Q3 2026 earnings call2026-10-29 · 2027HBMallocation and agreed target prices; HBM4revenue mix is not wafer/bit mix. No published company-level HBMprofit floor.
  43. SK hynix / TSMC HBM4 cooperation2024-04-19 · Base-die and packaging cooperation; relationship existence does not establish annual customer allocation.
  44. NVIDIA FY2026 Form10-K: manufacturing and memory suppliers2026-02-25 · Names memory suppliers includingSKhynix,Micron,Samsung; generic supply relationship does not prove qualification for every generation.
  45. NVIDIA DGX Rubin NVL8 system specificationavailable2026-11-17 · 8GPUs and approximately24kW system power. System scope is distinct from acceleratorTDP and wholefacility capacity.
  46. Intel Foundry power-delivery white paper2026-08 · Original Intel analysis offers power-scaling estimates. Not an NVIDIA TDP disclosure; used only as engineering cross-check.
  47. Microsoft Maia multigigawatt deployment plan2026-10-12 · 96accelerators/167kWrack concernsMaia300. Do not attach this rack ratio toMaia200. Multi-GW deployment starts2027; annual mix is not disclosed.
  48. Anthropic / Google / Broadcom compute update2026-05-06 · 5GW agreement begins coming online2027. Calendar phasing is analyst-assumed; do not add the3.5GWsubset again.
  49. Core Scientific Q2 2026 Form 10-Q: AMD direct leases and Neocloud credit support2026-07-28 · Note 15 subsequent events: July 27 execution. AMD directly leases 377 MW; a separate Neocloud leases 152 MW under lease-specific AMD credit support, including equipment protections, optional cure rights and specified material-default provisions. The 1,925 MW reservation right is not included in contracted capacity. Filing date verified on the issuer IR filing page as July 28, not the June 30 period-end.
  50. NVIDIA Q3 FY2027 financial results2026-11-17 US / 2026-11-18 Beijing · Revenue, data-center revenue, Rubin shipments; Q4 guide includes an additional week and assumes no China Data Center compute revenue.
  51. NVIDIA Q3 FY2027 management earnings-call transcript2026-11-17 US / 2026-11-18 Beijing · Management speech transcribed by Quartr: FY2028 growth outlook, financing clarification, allocation, CPO, and capital priorities; third-party transcript of primary speech.
  52. NVIDIA Q3 FY2027 CFO Commentary2026-11-17 · Pages 2-5: China revenue; Oct25 supply commitments, Neocloud conditions and guarantees. These are pre-transition quarter-end balances. Furnished EX99.2, 8-K accession 0001045810-26-000088; 10-Q not yet filed.
  53. NVIDIA expands commitments with supply-chain partners2026-11-17 · Kinsus substrate expansion, Amkor prepayments, SPIL advanced packaging; announcement and planned ramp dates, not completed capacity.
  54. NVIDIA export-control oversight committee announcement2026-11-17 · Board-level national-security and export-control oversight; no assertion about new laws or license outcomes.
  55. NVIDIA introduces Nemotron for Science2026-11-16 · Post-transition product announcement; supports current activity in open scientific models, not a quantified long-term spending or sales guarantee.
Version 1.4.0 · Independent industry research. Model assumptions and sources appear in the appendix; separate AI reviewers applied fundamental and quantitative frameworks.